Whether it’s in a value-driven community, over lunch, on your X and LinkedIn feeds, or in the latest business podcast, the conversation is the same: funding. Everyone is talking about how to get it. And if you’re torn between two ideas, a scalable startup on one hand and a solid traditional business on the other and wondering which one will actually make an investor reach for their chequebook, this article is for you.
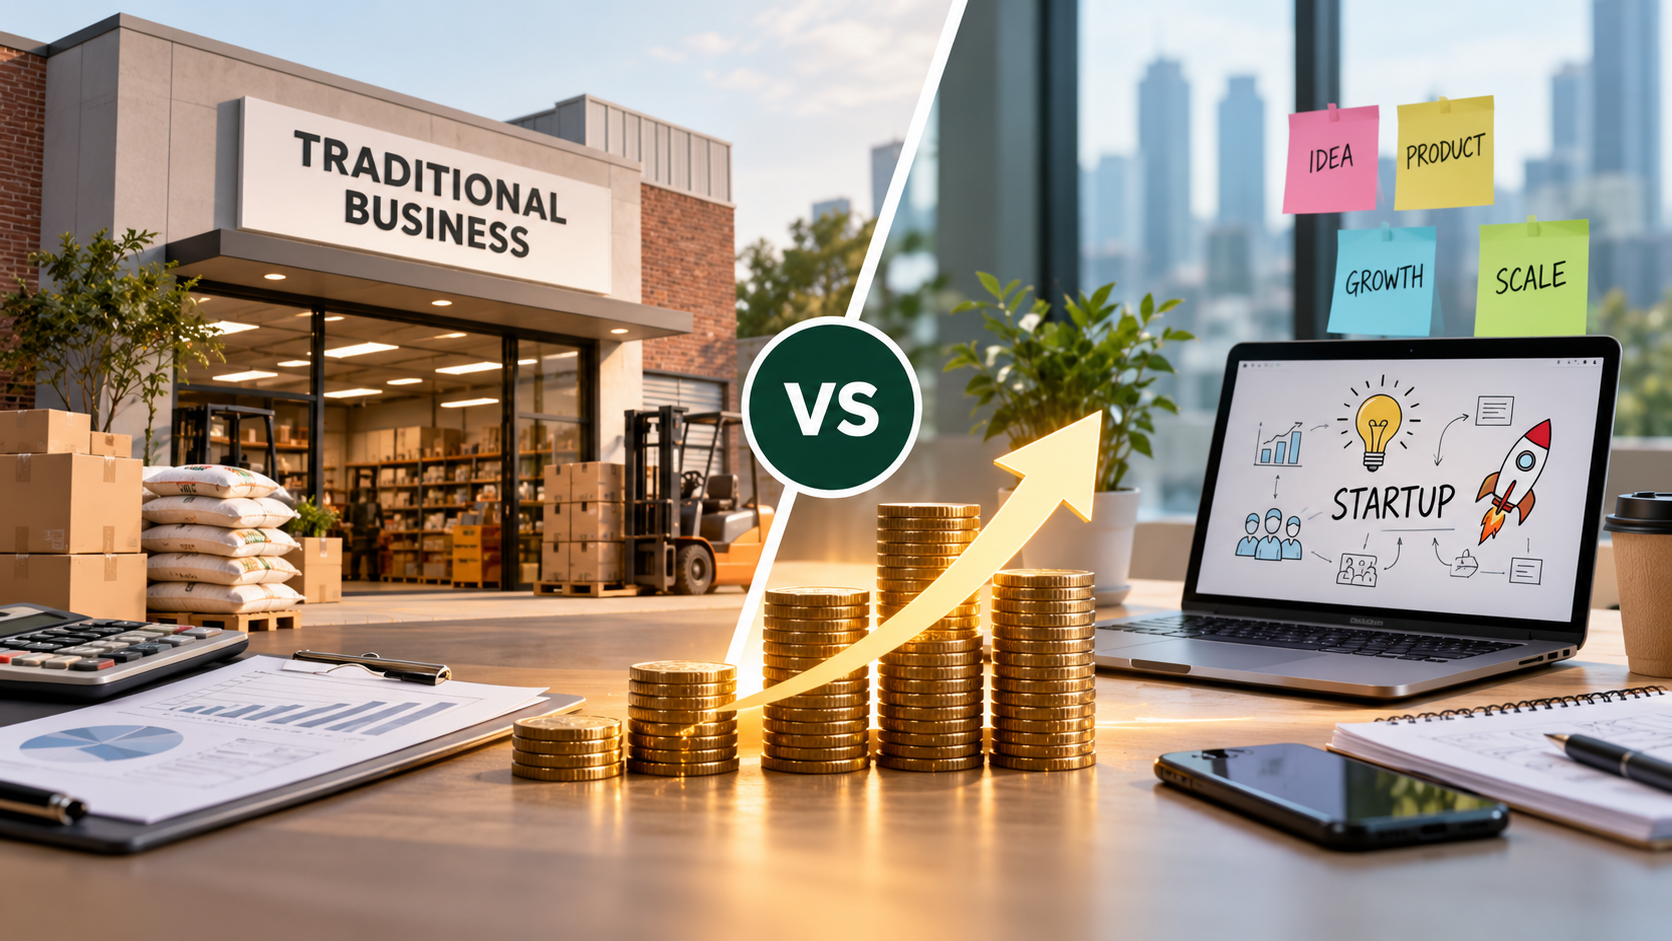
On one side, you have the seasoned entrepreneur running a steady, revenue-generating traditional business or even a chain of regional logistics hubs, a manufacturing plant, or a network of retail stores. On the other side, you have the visionary founder pitching a high-tech startup, a platform promising to revolutionize an entire industry with artificial intelligence, even if it hasn’t made a single dollar in profit yet.
Both founders are seeking the exact same thing: investor capital to fuel their growth.
However, if you put both founders in front of a panel of investors, you will quickly realize that “funding” is not a one-size-fits-all game. The real answer to which business type is most likely to get funded depends entirely on who is holding the chequebook, how risk is calculated, and what kind of return on investment (ROI) is expected.
Let’s pull back the curtain on how investors evaluate traditional businesses versus startups, unpack their distinct funding landscapes, and reveal which path gives you the highest probability of securing capital for your venture.
1. Defining the Playing Field: Core Differences
To understand investor appetite, we first need to establish clear definitions. While both types of ventures create value and generate employment, their underlying DNA, growth trajectories, and financial mechanics are fundamentally different.
| Feature | Traditional Business | Start-up |
| Growth target | Linear, steady, sustainable growth | Exponential, rapid scale |
| Business Model | Proven, tested market demand | Unproven, disruptive, or innovative |
| Profitable Timeline | Day one or early stage | Deferred in favour of rapid expansion |
| Primary Capital Need | Working capital, inventory, assets | Product dev, user acquisition, market |
| Main Risk Profile | Execution risk, market competition | Product market fit, technology risk |
The Traditional Business Model
A traditional business operates on proven business models within established markets. Think of a commercial real estate firm, an established bakery chain, an auto repair network, or a wholesale distribution company.
- Goal: Consistent profitability, cash flow stability, and steady market expansion.
- Motto: Build something reliable that yields predictable returns.
The Startup Model
A startup is a temporary organization designed to search for a repeatable and scalable business model. Think of early-stage platforms, software-as-a-service (SaaS) products, biotech firms, or fintech disruptors.
- Goal: Rapid market capture, high scalability, and massive market dominance.
- Motto: Fail fast, iterate quickly, and scale exponentially.

2. The Investor Spectrum: Who Funds What?
A major source of confusion for founders stems from treating “investors” as a single, uniform group. In reality, investors operate in vastly different asset classes with completely different mandates, risk tolerances, and target returns.
TRADITIONAL STARTUP
Commercial Venture Capital (VC)
Banks Angel Investors
Private Accelerators
Equity
Who Funds Traditional Businesses?
Traditional businesses appeal primarily to conservative capital providers who value cash flow and asset security over high-risk speculation:
- Commercial Banks & Lenders: Financial institutions look to fund traditional businesses if the particular business meets its requirements. They’re not interested in having a part of the business or sharing profit or loss, they lend businesses with agreement to receive loan amount + interest. To qualify for funding, a business has to provide collateral, debt service coverage ratios (DSCR), historical tax returns, and reliable cash flows.
- Private Equity (PE) Firms: These are non-bank financial institutions and asset managers. They look for mature, profitable traditional businesses with strong EBITDA (Earnings Before Interest, Taxes, Depreciation, and Amortization) that can be optimized or consolidated.
- Asset-Based Lenders & Government Small Business Grants/Loans: Provide capital backed by physical equipment, real estate, or inventory.
Who Funds Startups?
Startups target high-risk, equity-based investors looking for astronomical upside potential:
- Venture Capital (VC): Venture Capitalists are firms that collect large sums of money from rich individuals, companies, and institutions, put it in a pool of funds then they find promising startups with high growth potential. They invest a huge sum of money in exchange for equity (part ownership of the startup) with the hope that it grows very fast and becomes very valuable.
- Angel Investors: These are wealthy individuals who invest their personal money in early stage businesses. They’re usually successful entrepreneurs and founders along with their money, come with advice, connections, and mentorship. In most cases, they come in at a very early stage when the idea is still risky, before VC Firms will think it safe to invest. Unlike VCs, getting this kind of funding is faster and direct with less doubts, they invest by how well they know, trust and believe the founder.
- Venture Debt: There are institutions that provide funding for startups but the funds are not equity based but loan based. This is for founders who don’t want to give up ownership so they borrow and pay back with interest. This kind of funding is mostly offered to startups that have already raised VC funding and have steady revenue but don’t want to dilute their shares further.
- Accelerators: Accelerators are programs that help early stage startups grow quickly within a short period, usually from 3 to 6 months. They give a small amount of funding in exchange for 5-7% equity. They also offer training, intensive mentorship, office space, and introduce founders to a network of investors on Demo day. Examples are Y Combinator, Google for Startups, Techstars.
3. What Investors Look For: Cash Flow vs. Scalability
When an investor sits down to evaluate a business proposal, their decision framework hinges on two contrasting philosophies.
Traditional Businesses: The Power of Proven Economics
When traditional investors audit a business, they perform a backward looking and current state evaluation:
- Historical Profitability: Do the balance sheets and income statements show consistent top line revenue and net profit over 3 to 5 years?
- Tangible Assets: Does the company own machinery, land, vehicles, or inventory: The Power that can serve as collateral?
- Predictable Margins: Are the cost structures stable and easy to project?
Investor Perspective: “If I lend or invest $500,000 into this manufacturing business, the historical data proves they can pay me back with interest or yield a steady 12% to 18% annual return.”
Startups of Total Addressable Market (TAM)
Conversely, venture investors conduct a forward looking, highly speculative evaluation:
- Massive Market Size (TAM): Can this business address a billion dollar global market?
- Unit Economics & Network Effects: Once the software or platform is built, does serving user #100,000 cost virtually the same as serving user #1,000?
- Unfair Advantage / Proprietary Tech: Does the startup hold patents, unique algorithms, or deep network effects that make it difficult for competitors to copy?
Investor Perspective: “Nine out of ten startups I fund will likely fail or return zero. Therefore, the tenth startup must have the potential to return 50x to 100x my investment to make up for all the losses.”
4. The Verdict: Which is Most Likely to Get Funded?
Now we arrive at the million dollar question: Which one wins the funding game? The honest, data-backed answer is: It depends entirely on the type of capital being sought.
When it comes to overall capital volume available: traditional businesses over startups. If what we’re dealing with is venture capital allocation then startups over traditional businesses. Let’s take a look at these scenarios;
If we are looking at total capital volume, traditional businesses get it. If funding includes all forms of outside capital like bank debt, commercial credit lines, private equity buyouts, equipment financing, and government backed loans, traditional businesses win by a landslide.
Traditional businesses receive the vast majority of capital deployed globally every day. Why? Because banks and institutional lenders prefer low risk, asset-backed lending. A profitable plumbing franchise or an established medical clinic can easily secure a $500,000 bank loan, whereas an unproven software startup with no revenue will likely be turned away at the door by traditional bank loan officers.
When talking about funding that involves raising equity capital from VCs, angel investors, and tech syndicates, startups win handily. Venture capital funds are legally structured to hunt for explosive, non-linear returns. A traditional dry cleaning service or local restaurant group, no matter how profitable, is likely impossible to fund through traditional VC channels because it cannot double in size every 6 to 12 months or achieve a billion dollar valuation within 7 to 10 years.
5. How Founders Can Maximize Their Funding Success
Whether you are launching a tech platform or building a local supply chain enterprise, understanding how to position your company for the right investor class is critical.
If You Are Building a Traditional Business:
- Focus on Cash Flow & Debt Capacity: Your superpower is real, verifiable cash flow. Keep meticulous accounting records and focus on debt financing rather than giving away expensive equity early on.
- Target Private Equity or Debt Investors: Instead of pitching tech angels, build relationships with regional banks, commercial lenders, and private equity firms that specialize in middle-market buyouts.
- Emphasize Asset Protection: Clearly highlight your tangible assets, customer retention rates, and recurring revenue streams to mitigate risk for lenders.
If You Are Launching a Startup:
- Prove Traction & Product Market Fit: Show rapid user growth, high engagement rates, or strong pre-orders to demonstrate that people actually want what you are building.
- Articulate a Massive Market: Demonstrate clearly how your solution captures a significant share of a rapidly expanding multi-billion-dollar market.
- Seek High-Risk Equity Partners: Align your pitch with venture capital funds, angel syndicates, and industry specific accelerators whose mandates align directly with high growth disruption.
Final Thoughts
Neither business model is inherently superior; they simply serve different economic purposes and appeal to different capital pools.
If your venture promises steady profit, physical assets, and low risk, the deep oceans of traditional banking and debt financing are waiting for you. If your business carries high risk but possesses limitless scalability and disruptive power, the world of venture capital and angel equity is where you belong. The key to getting funded is not changing your business identity, iit is matching your venture’s DNA with the right financial partner.